Before you shop
Get pre-approved first.
A pre-approval tells you what you can comfortably spend and shows sellers your offer is real. I partner with Dave Waldschmidt of Canopy Mortgage, licensed in California.
Know the difference
Pre-qualified vs. pre-approved
They sound alike, but sellers treat them very differently.
Pre-qualified
A quick estimate based on what you tell a lender about your income, debts and savings. Nothing is checked yet, so it's a starting point, not something to make an offer with.
Pre-approved
The lender reviews your credit and documents like pay stubs, tax returns and bank statements, then gives you a letter with a loan amount. This is what makes your offer strong.
Fully underwritten approval
The strongest option. An underwriter reviews your file before you find a home, so only the house itself is left to approve. Ask Dave whether it fits your situation.
Loan options
Common ways to buy
Every buyer's situation is different. Dave compares your options side by side so you can choose.
Conventional
The most common loan. Some buyers can put down as little as 3%. With less than 20% down, you'll usually pay mortgage insurance until you build equity.
FHA
Backed by the Federal Housing Administration, with down payments as low as 3.5% and more flexible credit guidelines.
VA
For eligible veterans, service members and some surviving spouses. Often no down payment and no monthly mortgage insurance. I'm a Certified Military Expert, so ask me anything.
USDA
For homes in eligible rural and suburban areas. Often no down payment, with household income limits.
Jumbo
For loan amounts above the standard limit, common for luxury homes and estates. Expect stronger credit and reserve requirements.
Not sure?
That's normal. Tell Dave what you're hoping to buy and he'll walk you through what fits.
Start with Dave →
What to have ready
Gather these before you apply
Income
Your last 30 days of pay stubs and your last two years of W-2s or tax returns.
Savings
Two months of bank and retirement statements, every page.
ID
A driver's license or other photo ID for everyone on the loan.
Military buyers
Your DD-214 or statement of service, if you're using a VA loan.
Our lending partner
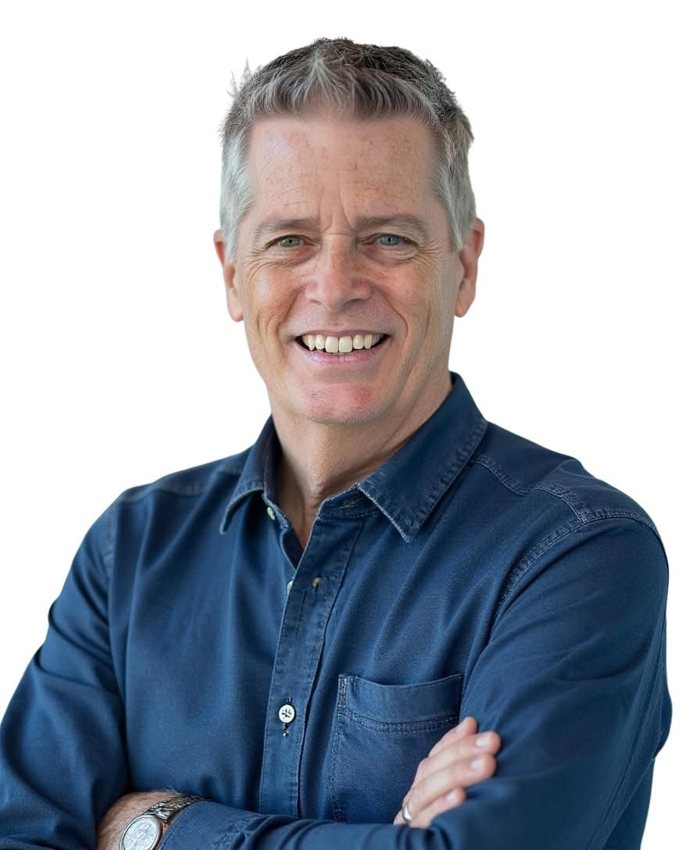
Meet Dave Waldschmidt
Dave is a Certified Mortgage Advisor with Canopy Mortgage and has worked in residential lending for decades. He focuses on strategy, not just the transaction: structuring a loan around your long-term goals and explaining the trade-offs of each option so you can decide.
He works closely with me so your financing and your home search move together, with clear updates the whole way.
Dave Waldschmidt, NMLS #304987, licensed in California (CA-DBO304987). Canopy Mortgage, NMLS #1359687. All loans subject to credit and property approval. Jennifer Sandvos Realty Group, brokered by Real Broker is a real estate brokerage, not a lender. You are free to choose any lender. Jennifer Sandvos Realty Group does not receive any payment or other compensation for referring you to Dave Waldschmidt or Canopy Mortgage.
Ready to start?
Dave's secure online application takes about 15 minutes, and he'll reach out to talk through your options.
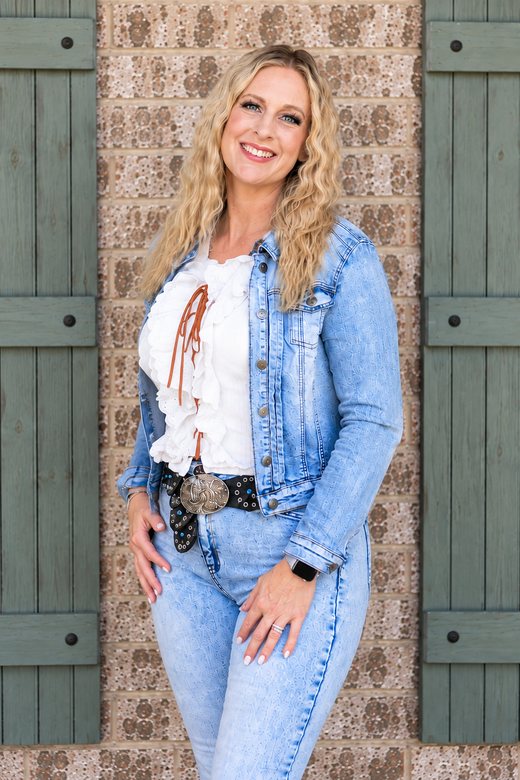
Rather talk with me first?
Questions about buying in Northern California? I'm happy to help, and I'll connect you with Dave whenever you're ready.